All Categories
Featured
Indexed Universal Life Options for Retirement
Comparing Term and Whole Life Insurance Advice
Comparing Term and Whole Life Insurance Advice
Table of Contents
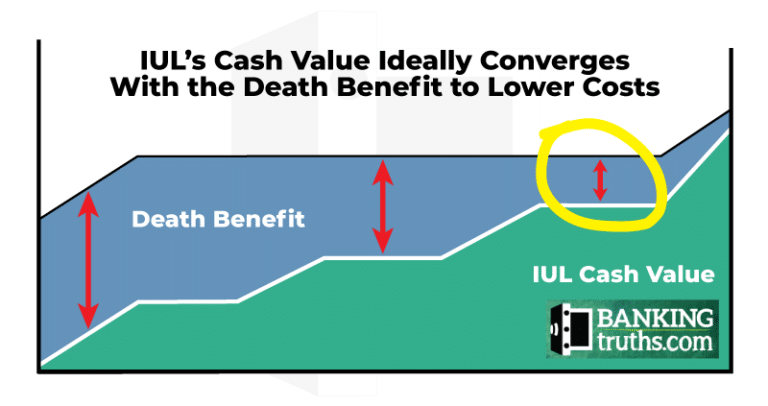
However, these very same Indexed Universal Life products will considerably underperform if they're light funded and/or their performance lacks. That implies that the internal charge load baked into the item is higher than it needs to be, and greatly reliant on efficiency to outrun the costs. These poorly created products that get sold to the unsuspecting masses are the reason you typically hear IUL is a continuous combo of debits and credits, so it's smart to know what both sides of the journal look like.
It's pretty standard these days for a lot of IUL policies to have some sort of participating loan option, where your money worth still has market exposure even while borrowing against it for emergencies or opportunities. Also, it's smart to think about the spread between whatever the loan rate is and the cap so you know what type of favorable arbitrage you can expect in bullish years.
So, having an integrated mechanism to catch this prospective arbitrage will be important in picking the best-performing IUL policy. There are IUL calculators to assist you figure out if you can anticipate long-term positive arbitrage on your cash worth over various timeframes throughout bull and bearish market. Exact same age, very same score, Same premiumDifferent companies, Various designs, Drastically various money valuesSee how your policy stacks up.
For these reasons,, who is remaining abreast of this rapidly altering market and can inform you to the most recent news and opportunities. It's not surprising that Penn Mutual ranks the highest of the very best IUL companies in regards to assurances given that they also provide the best-performing Whole Life policy, an item known for its assurances.
Numerous of Penn Mutual's indexed accounts featured an ensured 1% flooring, which indicates that even in down market years, you earn interest to offset the continuous expense of the death benefit. In spite of this 1% flooring, Penn Mutual still uses competitive caps on its S&P 500 methods. Unlike the other finest IUL business on this list, Penn Mutual does NOT offer Volatility Control Index techniques.
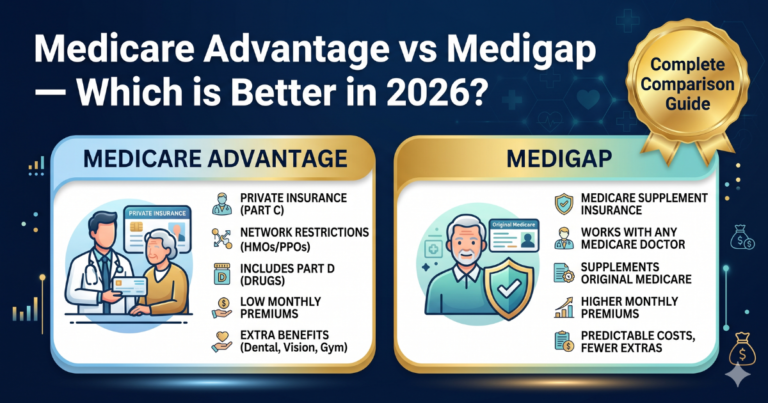
Selecting 2026 Medicare Options
(In case you missed it above, VCIs are algorithmic market timing methods handled by well-known financial investment banks with high internal costs and an absence of transparency). Competitive Caps on the S&P 500 (in some cases with a 1% floor rather of 0%)The capability to raise your S&P 500 cap (for an additional fee or spread of around 3%)Uncapped S&P 500 crediting methods for maximum growthWith Penn Mutual's contractually locked 6% policy loan rate for the life of its IUL policy, you can keep your cash worth working in the S&P 500 Index even while borrowing versus it for emergency situations or outdoors financial investment chances.
Allianz takes place to be the only on the list and a foreign stock company at that. It stands to stress that a German moms and dad business may not have allegiance to American insurance policy holders if economic times get tough, however others like the truth a foreign stock company has differed sources of incomes in diverse insurance coverage markets.
Insurance in Laguna Beach CAThis allows them to offer their "rate lock feature," where IUL policy owners can freeze whatever gains they have at any point throughout the year. Nevertheless, it's worth keeping in mind that you can only do this with their various volatility control indexes (VCIs) and not the pure S&P strategies. In reality, Allianz also has various charge options that enable you to increase your direct exposure to their indexed alternatives.
Allianz is among the finest IUL business due to the fact that of their varied set of IUL investment optionsIt's worth noting that I have actually been an Allianz insurance policy holder given that 2014, and I can confirm to the fact that my IUL caps and involvement rates aren't as competitive as what they've regularly provided on whatever their most current product is.
Protecting Family Wealth with Whole Life Insurance
For that reason, it's vital to stress-test how Allianz's IUL policy holds up at lower crediting rates compared to the other top Indexed Universal Life business. A wide assortment of exotic indexes to choose fromRate-lock function when utilizing the volatility control indexesAbility to be more aggressive with a 40% multiplier (for a 1% fee)Locked 5% loan rate to borrow versus any of the indexed accountsTheir "Index Lock" only works with Volatility Control Indexes, not the pure S&P methods.
That really is why Nationwide is one of the leading IUL business. Not just that, however they are a true mutual business, meaning they have no outdoors investors nor a holding company to siphon earnings to.

Latest Posts

Indexed Universal Life Options for Retirement

Life Insurance Policies Specifically for Military Veterans
Comparing Term and Whole Life Insurance Advice