All Categories
Featured
Essential Part D Selection Advice for Next Year
Final Expense and Burial Expense Planning

Finding the Best Individual Health Insurance Quotes
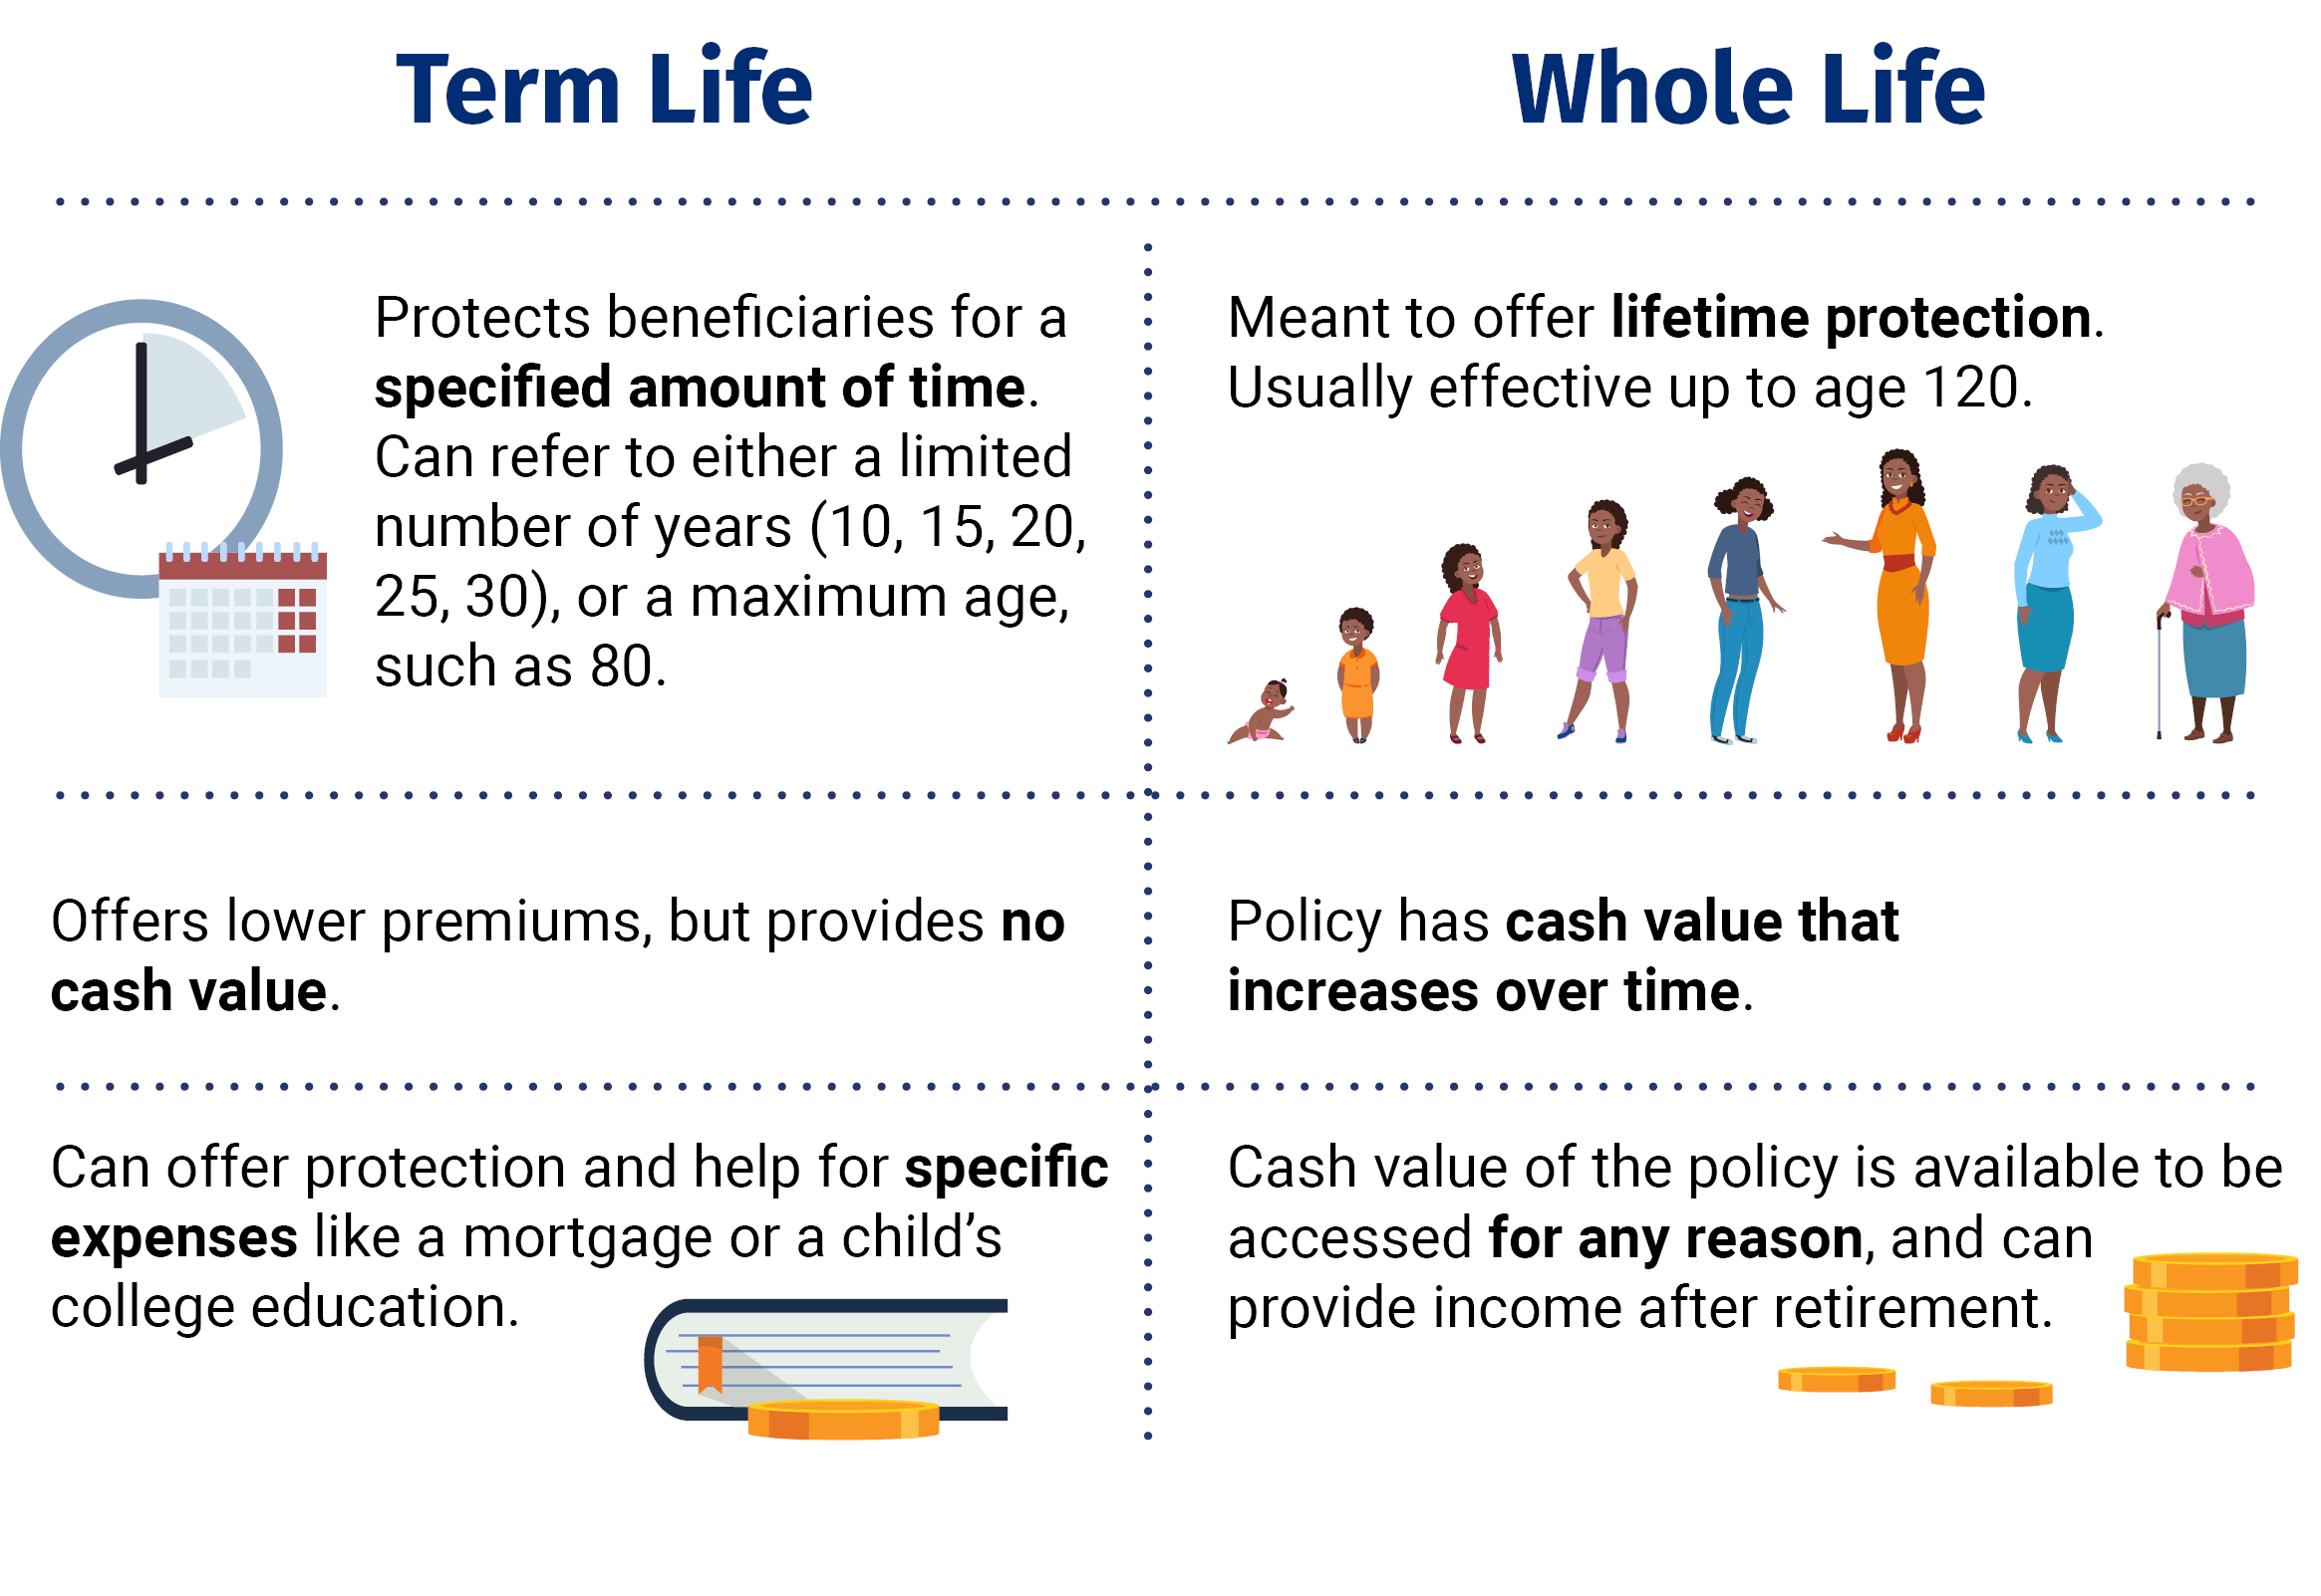
The cost of an indexed universal life insurance coverage policy differs, depending on factors like your age, where you live, your health and the coverage quantity you choose. According to one quote, a healthy, nonsmoking 34-year-old lady may pay in between$71 and $96 a month for an indexed universal life policy, assuming$250,000 of coverage. The same individual might pay$32 to$44 a month for a term life policy and in between $177 and$245 per month for a whole life policy.
Insurance in Colton CA
You might not require a life insurance coverage policy after you have actually paid off your debts and saved for your big monetary goals, like retirement and your kid's college education. In these circumstances, a term life insurance coverage policy with a different retirement fund and other cost savings vehicles may provide what you need, and at a lower price tag. As soon as you have a few quotes, you should: Compare coverage limitations, approximated regular monthly payments and administrative or management costs that come with each policy.
Rather, the insurance company utilizes the index as a criteria to figure out how much interest to credit to the cash worth part of your policy. If the index has a bad year, your credited interest might be lower(in some cases even 0%), depending on your policy's terms. If your policy credits the.
full 10Complete, your cash value could worth might $5,000 in interest before fees and costs charges.
For instance, expect your policy has a 10 %cap, and the marketplace index gains 15%that year. Even though the index increased by 15 %, your policy would only be credited 10 % before charges and other policy charges. Numerous IUL policies have a 0 %floor, meaning you won't lose cash worth just since the underlying market index has a negative year. If the index falls 18%, your credited interest may be 0%rather of -18%. That stated, a 0 %flooring protects you from market losses, not from policy expenses. An involvement rate determineshow much of the index's gain is credited to your policy. For example, if your policy has an 80 %involvement rate and the index increases 10%, you would receive 8%interest (80%of the index's gain), presuming no cap limits the return. If the involvement rate is 100 %, you would earn the full 10 %as long as it doesn't surpass the cap. Two policies tracking the very same marketindex can produce really various results depending upon how these functions are structured. Many indexed universal life policies let you choose between two types of survivor benefit: Your recipients receive a fixed survivor benefit throughout the life of the policy. As your cash worth grows, it generally ends up being part of that total survivor benefit rather than being paid in addition to it.

Latest Posts
Essential Part D Selection Advice for Next Year
Finding the Best Individual Health Insurance Quotes
Tips to Find Cheap Medical Insurance